

Affirm Is Now at Amazon UK's Checkout. Erica Olsthoorn Ran That Playbook in Canada First.
When Affirm entered the United Kingdom in November 2024, it did so with two launch partners: Alternative Airlines, a flight-booking site, and Fexco, an Irish payments processor. Useful names, but not household ones. By the autumn of 2026, the picture looked different. Affirm went live at Wayfair UK in February, across UK merchants on Stripe from July, at Costco UK on 15 September, and at Amazon.co.uk on 23 September. That climb — from willing early adopters to national retailers — is one Erica Olsthoorn has made before. She made it in Canada, for PayBright, the company Affirm acquired in January 2021 for approximately C$340 million.
Selling an unfamiliar payment method to a national retailer meant asking Olsthoorn's buyers to rethink more than checkout. At PayBright, she was helping retailers decide whether buy now, pay later could become a customer-acquisition and growth tool at a time when many executives still viewed the category mainly through payment cost and credit risk. Her enterprise book eventually included Apple, Hudson's Bay, Sephora and 50-plus enterprise partners.
"I build the commercial engine that takes a company into a market that barely exists yet," Olsthoorn says.
Payments Canada later reported that 8 percent of surveyed merchants accepted buy now, pay later, while 48 percent of those that did not offer it were interested or extremely interested in doing so. Interest was running well ahead of adoption.
British merchants are now somewhere further along the same curve. In a survey Affirm published in September 2026, 79 percent of UK small and medium-sized businesses said customers expect more than debit card payments at checkout, and 43 percent said they worried about competing with larger retailers as those expectations rose. Among those already offering flexible payments, 85 percent reported better conversion and 84 percent reported higher order value.
For Olsthoorn, the commercial problem in Canada was turning curiosity into a case that could survive scrutiny from large retailers with established payment systems and multiple internal stakeholders. That meant reframing the conversation — moving buy now, pay later beyond a narrow discussion about transaction expense or credit exposure and connecting it to customer acquisition, conversion, average order value, and the economics of a retailer's broader relationship with its shoppers.
Hudson's Bay became the clearest example of that work. She built a co-marketing and return-on-investment framework around the account. The commercial case evaluated the partnership through customer-acquisition cost and lifetime value instead of relying only on transaction margin. That changed the discussion from what the payment option cost the retailer to what it could contribute to customer growth and purchasing behaviour. It also gave stakeholders with different priorities a shared set of business outcomes to evaluate.
Adam Powell, an omnichannel and customer-experience leader at Hudson's Bay, says Hudson's they saw average order value increase by 25 percent or more after implementation, while conversion also rose. The results became a company-wide benchmark at PayBright. For an emerging payment category, the outcome gave PayBright something that had been difficult to offer earlier: operating evidence from a major retailer showing measurable changes after adoption. Interest in a consumer trend was not enough to change the way a national retailer handled payments. The proposal had to connect PayBright to economics each stakeholder could evaluate, from acquisition cost to customer lifetime value. That became the commercial work behind the sale.
The approach contributed to a much larger enterprise book. Olsthoorn helped grow PayBright's Canadian enterprise business from roughly C$5 million to C$75 million-plus in annual recurring revenue, an increase of approximately 15 times. Her work centred on the enterprise commercial business and the major retail relationships she developed. By the time Affirm announced its agreement to acquire PayBright in December 2020, the company's wider merchant network had expanded to more than 7,000 domestic and international retailers.
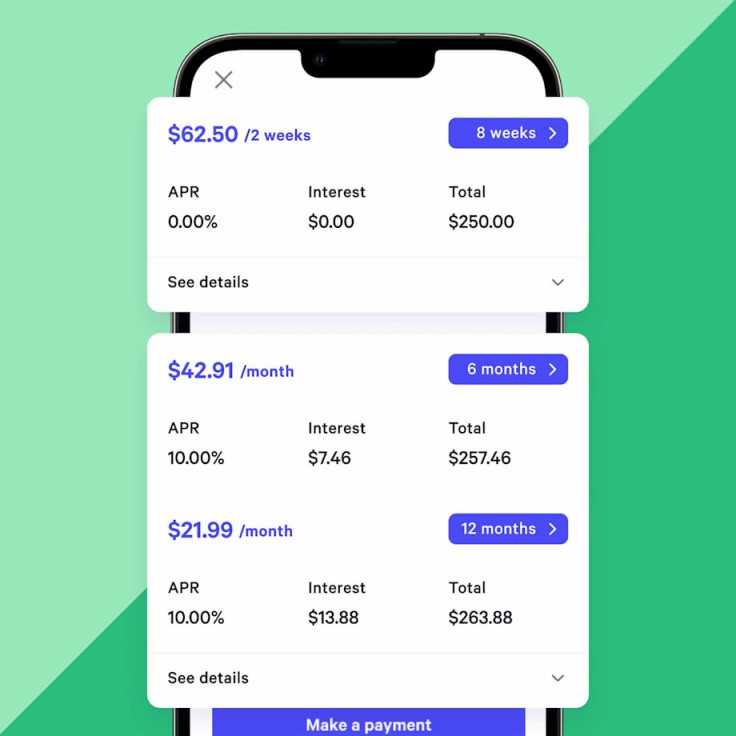
What is different in Britain is the floor beneath the conversation: since 15 July 2026, UK buy now, pay later agreements have required FCA authorisation and proportionate affordability checks on every purchase, with Section 75 joint liability above £100 and access to the Financial Ombudsman. Compliance cost is now a line in any merchant's business case — 51 percent of the small businesses Affirm surveyed named it as a concern — but the underlying question a retailer asks has not changed. It is still what the option contributes, measured against what it costs.
For Olsthoorn, the PayBright period established a pattern she would repeat in later industries: entering before the commercial playbook was settled and translating an unfamiliar proposition into business terms a major customer could evaluate. At PayBright, that work happened as buy now, pay later moved from an emerging payment idea toward broader retail adoption.
The category eventually became familiar. Her job was to sell it before that familiarity existed — and Britain's national retailers are now being asked a later version of the same question.
Sources for the new UK facts
| Fact | Date | Source |
|---|---|---|
| Affirm entered the UK with Alternative Airlines and Fexco as launch partners; the UK is its first market outside North America | 3–4 Nov 2024 | PaymentsJournal |
| Wayfair UK and Canada expansion | 6 Feb 2026 | Retail Technology Innovation Hub |
| Stripe UK partnership announced, live from July 2026 | 2 Jun 2026 | PYMNTS |
| Costco UK partnership | 15 Sep 2026 | Retail Technology Innovation Hub |
| Amazon.co.uk launch: Pay-in-3 at 0 percent, or up to 48 months at 22 percent representative APR, £50 minimum basket, Section 75 cover above £100 | 23 Sep 2026 | Affirm investor relations |
| UK SME survey: 79 percent checkout expectation, 43 percent competitive worry, 85 percent conversion, 84 percent order value, 51 percent compliance cost | 9 Sep 2026 | Intelligent SME Tech |
| FCA rules live 15 July 2026: authorisation, affordability checks on every purchase, Section 75 above £100, Financial Ombudsman access; roughly 11 million UK users | Confirmed Feb 2026, live 15 Jul 2026 | MoneySavingExpert |
| PayBright acquisition for approximately C$340 million, completed January 2021 | Dec 2020 – Jan 2021 | Affirm Holdings |
© Copyright IBTimes 2026. All rights reserved.