

'Social Insecurity': 'The Ramsey Show' Warns Americans Over 50 Who Rely on Social Security
A $2,830 monthly retirement income gap could require about $849,000 in savings under the 4% withdrawal guideline

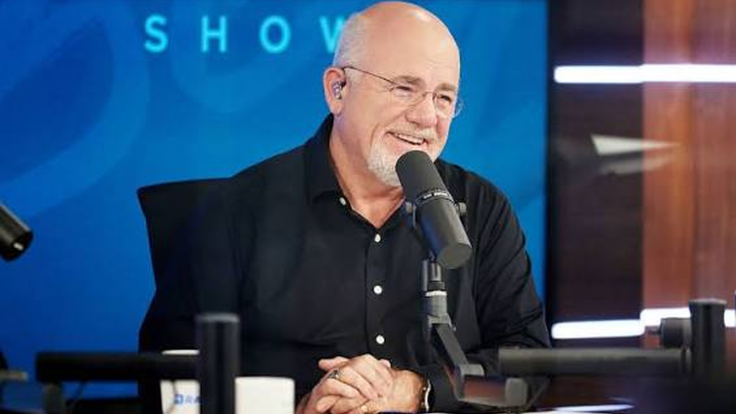
Americans planning for retirement may need to consider how Social Security benefits, personal savings, and household expenses fit together.
During the 15 October episode of The Ramsey Show, host Dave Ramsey used the phrase 'social insecurity' while discussing retirement planning and household budgeting. 'You don't want to be on social insecurity. That's completely ridiculous. Of course, you need to save for retirement.' Ramsey said during the episode, 'Build a Life That Doesn't Depend on Debt.'
His comment was part of a broader discussion about financial planning, not a specific warning directed at Americans over 50. However, the issue remains relevant to workers approaching retirement.
Social Security Benefits Are Rising in 2027
The Social Security Administration announced a 3.6% cost-of-living adjustment for 2027 on 14 October. The increase will apply to benefits beginning in January, with the average monthly retirement benefit for retired workers expected to reach $2,170. This is an average, not a guaranteed payment. Individual benefits depend on factors such as earnings history and the age at which a person claims retirement benefits.
Housing, food, utilities, insurance, and healthcare all affect retirement costs. For example, a household with a hypothetical monthly budget of $5,000 and one $2,170 retirement benefit would face a $2,830 shortfall to cover through other income, savings or reduced spending. Under the commonly cited 4% withdrawal guideline, a $2,830 monthly shortfall amounts to $33,960 annually. Supporting that initial withdrawal would require approximately $849,000 in savings. This is a simplified illustration, not a guarantee that the money would last throughout retirement.
The SSA also lists a maximum monthly retirement benefit of $4,188 in 2027 for someone retiring at full retirement age. Qualifying for that amount requires an eligible earnings history, and most retirees should not assume they will receive the maximum.
Workers Over 50 May Have Options to Increase Savings
Workers in their fifties may still have time to strengthen their retirement savings, depending on their income and financial commitments. Consider a 55-year-old with $244,900 saved who plans to retire at 67. Assuming a 7% annual return and no additional contributions, the balance could grow to approximately $551,562 over 12 years. Adding $8,000 at the end of each year could increase the projected balance to about $694,669, supporting an initial monthly withdrawal of roughly $2,316 under the 4% guideline.
Contributing $32,500 annually instead could produce a projected balance of around $1.13 million under the same return assumption. These estimates are illustrative and exclude inflation and taxes. Actual results will depend on investment performance, fees, and contribution timing.
The Internal Revenue Service sets the employee contribution limit for most traditional and safe-harbour 401(k) plans at $24,500 for 2026. Eligible workers aged 50 and over can make an additional $8,000 in catch-up contributions. Eligible participants aged 60 to 63 can qualify for a higher catch-up limit of $11,250, bringing the potential total to $35,750. Plan rules and eligibility requirements apply. Not everyone can afford to contribute the maximum, particularly when housing, healthcare, and family expenses compete for income.
Debt Can Increase Retirement Income Needs
Outstanding debt can leave retirees with less money for essentials and unexpected expenses. Mortgage payments, car loans, and other obligations may increase the income needed after leaving work. Under the 4% guideline, an additional $1,000 in monthly spending represents $12,000 annually. Funding that amount through portfolio withdrawals would require approximately $300,000 in savings.
This is a simplified calculation, not a universal retirement target. Paying down debt may reduce future expenses, but people should weigh interest rates, emergency savings, and other financial priorities before deciding how quickly to repay what they owe.
How to Review Retirement Readiness
People approaching retirement can check estimated benefits through their personal Social Security accounts and compare them with a realistic household budget. Reviewing workplace contributions, catch-up options, outstanding debts and expected payoff dates can also help identify potential income gaps.
Ramsey's remark highlights the importance of retirement planning. The savings required will depend on each household's expected benefits, expenses, and other sources of income.
© Copyright IBTimes 2026. All rights reserved.