

The Hidden Fees That Can Turn a Cheap Loan Into an Expensive One
Set-up charges, administration fees, repayment periods and missed-payment penalties can significantly affect the amount borrowers ultimately repay
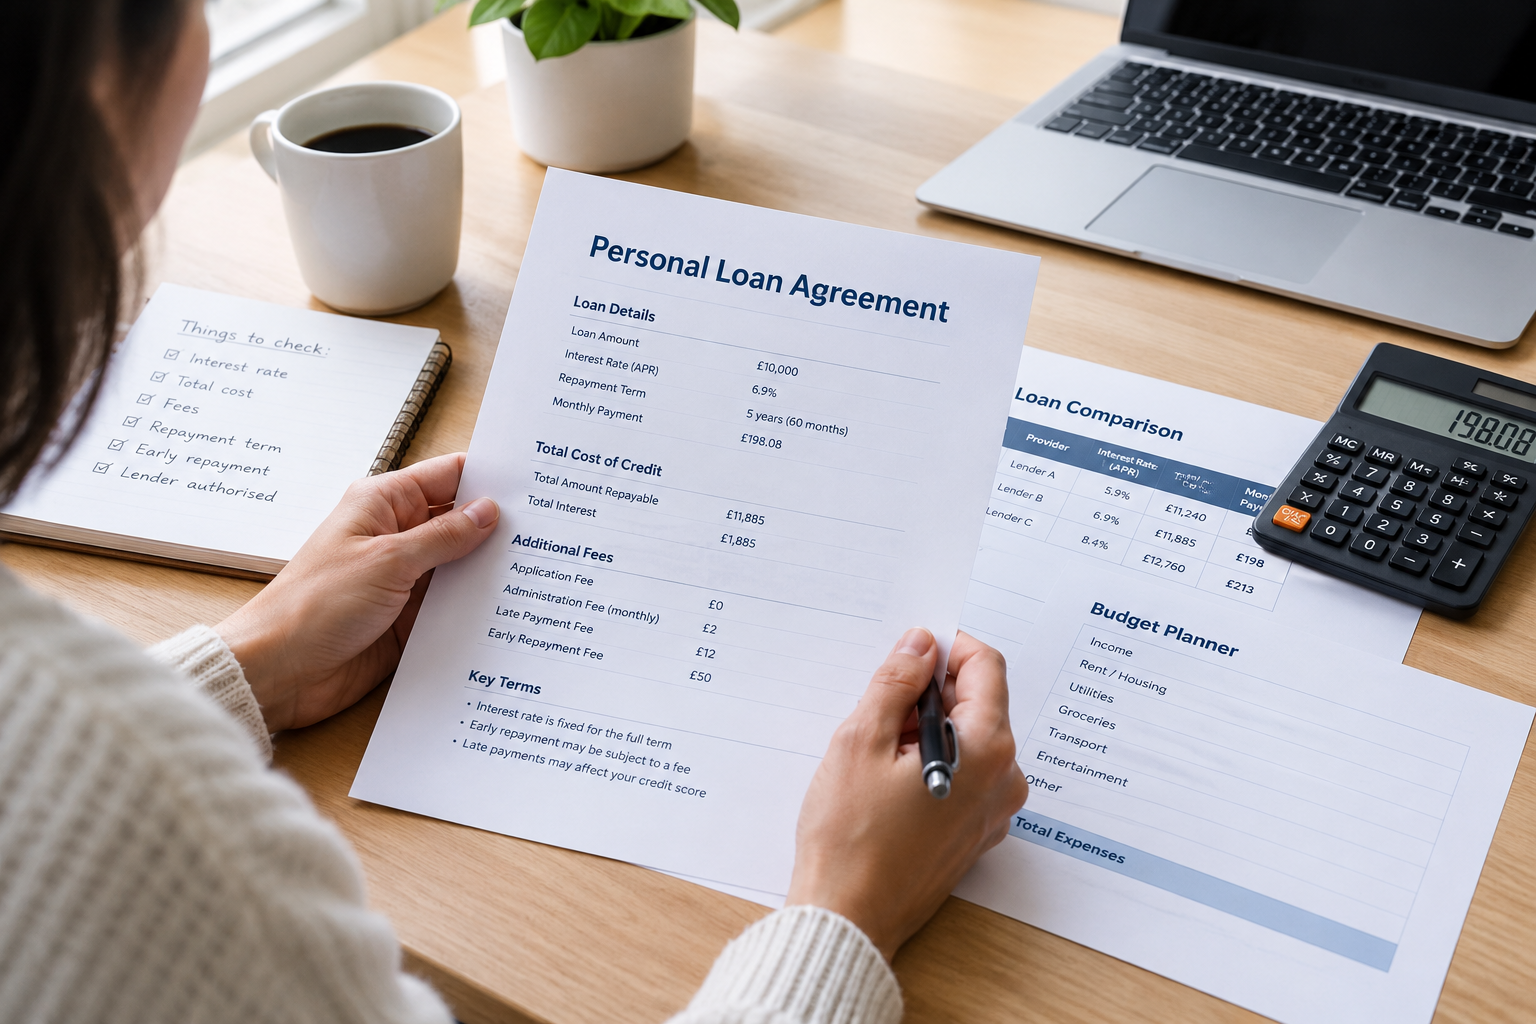
When individuals compare personal loans the interest rate is the first thing they look at. A lower rate does in fact make the borrowing less expensive, but it doesn't tell the whole story. Also included in the agreement may be other fees which although small do in the end affect the total amount a borrower repays.
Understanding these costs before signing a credit agreement is therefore important. The same principle applies whether somebody is considering a personal loan in the UK or a consumer loan in Norway. The terminology as well as rules can differ between countries, but the basic question remains the same: What is the total cost of the loan?
Why the Advertised Rate Is Not the Whole Cost
A loan may seem affordable when it has a low interest rate or a nice low monthly payment. But the monthly charge does not tell the whole story.
There may be set up fees, administrative charges, annual account fees, or other expenses related to the agreement. Also a long term repayment plan may see total interest go up although the monthly payments may seem more manageable.
Choosing a loan therefore involves more than looking at the headline rate. In Norway for instance the Consumer Council reports that the effective interest rate includes additional charges which in turn makes this measure more useful when you are between which to put your money.
Common Fees Borrowers Should Check
One option for a cost is an origination or arrangement fee. This may come up at the time of issue of the loan. As per the terms of the agreement it may either be taken out of the amount which goes to the borrower or added to the total cost.
Another type of charge is a regular account or administration fee. Which may be a small monthly amount but over the years it adds up. For example a £5 per month charge will total to £300 over a period of five years before all other borrowing costs are included.
Borrowers also should review the agreement which details late payment fees. To miss a payment may cause for additional fees to be applied and also may affect a person's credit record. The FCA's consumer credit rules require that which is relevant to missed payments and apply charges be presented to customers.
Also in some cases it can be seen that early termination of an agreement may bring about costs. What applies for early payment of a loan varies by the particular loan in question and what the rules say, thus it is not true that early payoff of a loan is always free.
Comparing UK Personal Loans and Forbrukslån
In Norway the term forbrukslån is a common one for consumer borrowing. Also in that which pertains to consumer advice from the Norwegian authorities great stress is put on checking the effective interest rate, total cost and repayment schedule which in turn is not the case when only the nominal interest rate is looked at.
In the UK personal loan borrowers also must go over all the details before they agree to it. The Financial Conduct Authority reports that lenders and brokers are to give out full pre contract info which includes the main costs and risks which in turn gives the customer time to go over the info and ask questions.
It is that which which is to be put forth that a loan must be evaluated at face value which includes all related costs and terms - and not just the figure which is put out in advertising.
Look Carefully at the Small Print
A loan agreement can run to many pages, but that does not mean you should skip them. Pay close attention to the payment schedule, fees, interest rate calculation, what happens in case of a missed payment and what the terms are for making changes to the agreement.
It also provides value to calculate out what the total amount which will leave your account over the term of the repayment will be. This gives a better picture than looking at the monthly instalment by itself.
For example there is a £3000 loan which may at first appear doable in terms of the monthly payments. Yet if the pay back term is made much longer, the customer may end up paying considerably more.
The same approach applies when researching saladmoney as a source of information about personal-loan costs. In terms of what is put out there in the open the easy thing is to see the low advertised numbers but that is not the issue the issue is what that full agreement brings to the financial table.
Be Careful With Upfront Loan Fees
Not all fees related to a loan are in fact suspicious. Also pre loan requests for money which turn out to be unexpected require special care.
The FCA reports on loan-fee fraud which is a scheme where scammers take an upfront payment and then do not provide the promised loan. Also they say to check that a firm is authorised and that its contact info matches what the regulator has.
Citizens Advice also says to check that a lender is authorised by the FCA before you take out a personal loan.
This distinction is important: A legitimate charge as presented in a credit agreement is different from an unexpected payment which is put forth by someone claiming to be a lender.
Consider the Effect of the Repayment Period
A loan's duration will greatly affect what that money ends up costing you in total. Which will be broken into smaller regular payments, extending the life of the loan may see the individual actually pay out over a longer time. But also this will give them a lower payment per period as interest still has to be repaid for those extra years.
For that reason which is true today borrowers should see to it that the repayment term fits their financial situation. A payment which may be easy to handle at present still has to remain within their means through the term of the agreement.
Norway's Consumer Council also puts forth that which is the borrower is able to manage the set payments and is aware of the total cost before entering into the agreement.
Financial Information and Personal Data
Applying for credit also points out that applicants share personal and financial info. Applicants may present ID details, income info, bank statements or other docs at the time of application.
Anyone that has issues with how the info is collected or processed can look at the company's privacy policy and related data protection info.
As for questions which come up regarding privacy rights or personal info handling, specialist GDPR solicitors may be able to give you legal advice, which is to say that data protection and loan pricing are separate issues.
A Better Way to Assess a Loan
Before you accept any loan offer, do a quick check:
- What is the interest rate?
- What is the total cost of credit?
- Are there set-up or founding fees?
- Are there recurring administration charges?
- What happens if a payment is late?
- Can prepayment of the loan be done and what are the terms?
- What is the total amount to be repaid?
- Does the repayment term fit the borrower's budget?
- Is the lender or broker properly authorised?
Spending a few moments on these questions will bring out costs which are often overlooked when attention is paid only to the advertised rate.
In effect what borrowers should do is look at the total agreement when talking about loans not just at a single appealing number.
A loan which has a higher interest rate but has lower additional fees may in fact end up being cheaper than one which at first seems to be a better deal. By reading the terms fine print and comparing the total pay back rates borrowers can get a better picture of what they are getting into.
© Copyright IBTimes 2026. All rights reserved.