

Two Mining Stocks an Investor Would Buy as Carney Courts Global Capital Despite Persistent US Trade Tensions
Motley Fool Canada's Jitendra Parashar notes Agnico Eagle's stronger earnings and Franco-Nevada's upside from higher commodity prices in his analysis
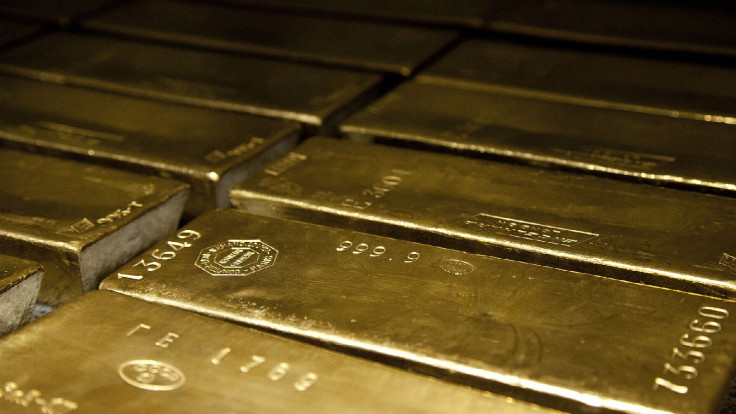
Two Canadian mining stocks, Agnico Eagle Mines and Franco-Nevada, were thrust into the spotlight on 30 October 2026 after Motley Fool Canada columnist Jitendra Parashar flagged them for investors seeking precious-metals exposure as Prime Minister Mark Carney courts global capital amid unresolved US trade tensions.
Both Toronto-based companies were highlighted as potential beneficiaries of foreign investment while Ottawa attempts to draw long-term money into Canada's energy and resources sector.
Carney hosted international investors at the Canada Investment Summit in Toronto on 14 and 15 September. According to the Canadian government, attendees represented nearly 30 countries and managed more than $100 trillion (approximately £74.7 trillion) in assets.
The gathering formed part of a wider federal effort to attract capital into energy, natural resources and other industries.
However, diplomatic uncertainty remains. On 28 October, Carney said Canada was not yet in a position to reach a trade agreement with the United States.
According to The Canadian Press, he maintained that Ottawa would only pursue an agreement that served Canadian interests.
Against that backdrop, Parashar identified two established mining businesses in his 30 October investment column. His selections were independent investment opinions, not endorsements from Carney or the Canadian government.
Why Agnico Eagle Tops This Mining Shortlist
Agnico Eagle Mines Limited, listed on the Toronto Stock Exchange under AEM, operates gold mines across Canada, Australia, Finland and Mexico. Its financial position and development projects were central to Parashar's assessment.
In the 30 October analysis, Agnico Eagle shares were quoted at C$256.08 (approx. €164.20 and £136.87), representing a 17 per cent annual increase. The column placed its market capitalisation at C$129.3 billion (approx. €82.91 billion and £69.11 billion), with an annualised dividend yield of roughly 1 per cent.
Those figures were historical market snapshots rather than independently verified live quotations.
The company's third-quarter earnings release, published on 28 October, showed net profit increasing 28 per cent year on year. However, gold production declined approximately 6 per cent to 814,012 ounces.
Higher gold prices supported earnings despite lower production. Agnico Eagle reported an average realised gold price of US$4,264 (approx. €3,820.97 and £3,184.78) per ounce, nearly 23 per cent above the previous year's level.
Rising labour, diesel and royalty expenses also affected operations. Consequently, stronger earnings should not be mistaken for increased mining output or reduced operating costs.
Agnico Eagle ended September with approximately US$3.4 billion (about €3.05 billion and £2.54 billion) in net cash. It also returned US$478 million (approximately €428.34 million and £357.02 million) to shareholders through dividends and share repurchases.
Its development pipeline includes Hope Bay, Odyssey, Upper Beaver and Detour Lake. These projects could support future production, although their contributions depend on construction progress, operating conditions and investment requirements.
Near-term production expectations remain restrained. Agnico Eagle anticipates 2026 output near the lower end of its 3.3 million to 3.5 million-ounce guidance range, partly reflecting adjustments at Canadian Malartic.
Franco-Nevada: Royalty Route To Mining Exposure
Franco-Nevada Corporation, trading on the Toronto Stock Exchange under FNV, provides an alternative to conventional mine ownership. Rather than directly operating mines, the company earns revenue through royalty and streaming agreements linked to production.
This structure reduces direct exposure to certain operating expenses, including labour, equipment and fuel. However, Franco-Nevada remains vulnerable to commodity-price movements, production disruptions and risks affecting its operating partners.
Parashar's 30 October column quoted Franco-Nevada shares at C$334.13 (approximately €214.24 and £178.59), following a 28 per cent annual increase. Its reported market capitalisation was C$64.2 billion (approximately €41.17 billion and £34.31 billion), alongside a dividend yield of approximately 0.7 per cent.
The financial figures also provide context for the columnist's interest.
According to Franco-Nevada's second-quarter earnings release, published on 11 August, revenue increased 57 per cent year on year to US$580.9 million (approx. €520.54 million and £433.87 million).
The improvement reflected higher commodity prices and an 18 per cent increase in gold-equivalent ounces sold. Quarterly net profit rose 43 per cent, while operating cash flow increased 12 per cent.
Franco-Nevada has continued expanding its royalty portfolio, including interests in Canada and Australia. Existing agreements involving Côté Gold, Candelaria and Tocantinzinho also contribute to its longer-term growth prospects.
Nevertheless, its exposure to Cobre Panamá illustrates the risks associated with royalty investments.
Full-scale mining remains suspended, although Panamanian authorities have permitted processing of previously extracted stockpiled ore. The mine's longer-term future remains uncertain, with potential operating arrangements subject to further government decisions and negotiations.
Franco-Nevada's third-quarter results are scheduled for 11 November 2026, making its second-quarter figures the latest quarterly earnings available when Parashar published his column.
Both companies have demonstrated earnings growth, but neither is insulated from commodity fluctuations or operational setbacks. Their recent share-price increases also make valuations important when assessing potential returns.
For investors, the distinction is straightforward: Agnico Eagle operates mines directly, while Franco-Nevada earns revenue through production-linked agreements. Whether either delivers further gains will depend on financial performance, market conditions and the prices investors pay.
© Copyright IBTimes 2026. All rights reserved.