Smart or Risky Move? Woman Drowning in $40,000 Credit Card Debt Empties Her 401(k) to Pay Off Half
Wilson spent up to $6,000 a month on her credit cards during her trip despite losing her job

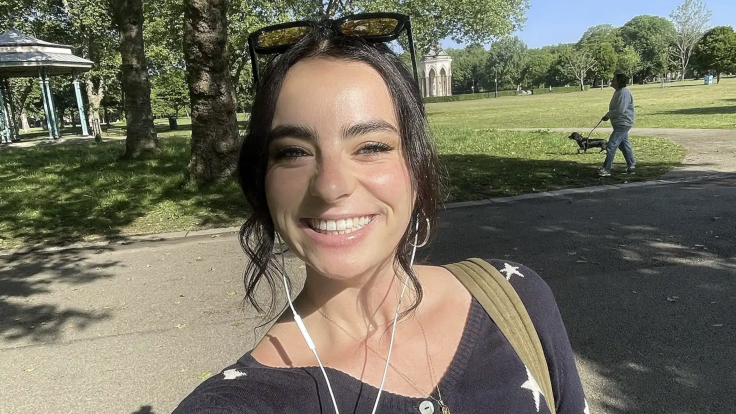
A dream trip to Europe left Hailey Wilson with $40,000 in credit card debt and a $1,300 monthly minimum payment she was struggling to keep up with.
With a personal loan unavailable and a 0% balance-transfer card out of reach because she had already maxed out her lines of credit, the 29-year-old made a controversial choice: she emptied her old 401(k) to wipe out about half the debt.
Two months into the Europe trip that started in May 2025, she lost her job as a contracted content creator. With non-refundable travel plans already in place and only a small amount of income coming from a client, she turned to her credit cards to cover the gap.
Minimum payments were doing little to bring the outstanding balances down because of the interest accumulating on the debt. She even considered bankruptcy at one point.
After speaking with a friend who had previously withdrawn retirement money and rebuilt her savings, Wilson decided to access her own old 401(k). When she checked the account after returning home from Europe, it had $28,650 in a combination of Roth and pre-tax funds. In May 2026, she withdrew all of it.
After taxes, fees, and penalties, she received a little more than $24,000 and used $21,000 of it to pay off roughly half of her credit card debt. The decision dramatically reduced her monthly payments and gave her a sense of relief, which she views as a financial reset.
Wilson is now freelancing, working in social media management and offering astrocartography readings, while also building a wellness community. Now, she is focused on creating an emergency fund and eventually rebuilding her retirement savings. She has not yet restarted 401(k) contributions because she wants to understand her options as a freelancer first.
Her spending habits have also changed. Rather than spending first and saving whatever remains, Wilson says she now prioritises saving for her future.
Former IRS Agent Says 'Never Touch Your 401(k)' is Bad Blanket Advice
Breaking into your 401(k) in your early working years is seldom recommended. Not only does it impact the compounding effect on your retirement savings, 401(k) withdrawals before the age of 59½ can attract a 10% additional tax, unless an exception applies. The distribution may also be subject to ordinary income tax.
The IRS also warns that hardship withdrawals permanently reduce the amount available for retirement. They generally cannot be repaid to the plan or rolled into another retirement account.
However, former IRS agent Natasha Verela has challenged the conventional advice surrounding retirement withdrawals.
Verela, 47, recently told PEOPLE that she considers 'never touch your 401(k)' among the worst blanket pieces of financial advice. She personally withdrew retirement savings to pay off $85,000 in student loans.
'Take the money out of your 401(k), especially if you are in your mid to late 30s. You have time to recoup regardless of what you might think. Pull it out. Pay any taxes if you can. If you have real estate or any business losses, you can offset those with the tax liability, and take the hit now,' she told the media outlet.
She argues that someone in their 30s or 40s carrying substantial debt may have decades to rebuild retirement savings, while continuing to carry expensive debt can keep consuming income.
'I would take the hit, because when you're older, you're not going to want to work nine, 10 jobs just to pay off debt. Your strongest earning years are not at 50 years old. You're physically stronger when you're in your 30s, you're mentally stronger on average, and the last thing you want is to have to play catch-up in your 40s,' she had said.
Her argument is not that everyone should empty their retirement account. Instead, people should carefully assess their own circumstances rather than blindly follow generic financial rules.
In all, Wilson's story could be less about whether emptying a 401(k) is smart or stupid, and more about the trade-off she chose: reducing high-interest credit card debt immediately while sacrificing retirement savings and accepting the tax consequences.
For her, it created breathing room. However, the same math could look very different for someone with a different income, debt interest rate, age, tax position, retirement balance, or emergency savings.
© Copyright IBTimes 2026. All rights reserved.
- Recommended For You