Suze Orman's Wife Paid $150K Into an Insurance Policy for 10 Years, Then Discovered Its Cash Value Was $50K
Whole life insurance combines lifelong coverage and cash value, but premiums don't go entirely toward savings

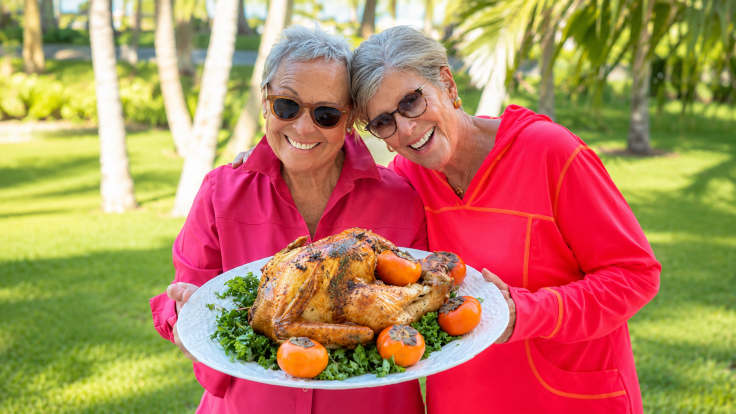
For 10 years, Kathy 'KT' Travis, a former television producer and the wife and business partner of personal finance expert Suze Orman, paid $15,000 a year into a whole life insurance policy she believed could help fund her retirement. Orman is a prominent US personal finance author, television personality and host of the Suze Orman's Women & Money podcast. Travis also regularly appears alongside her.
According to a 'Suze School' episode, Travis said the policy had accumulated about $50,000 in cash value after she paid $150,000 in premiums over 10 years. The episode was later revisited in a 'Classic Suze School' rerun.
The $100,000 gap between premiums and reported cash value prompted questions about the policy, although it does not necessarily represent a $100,000 loss. Travis said she bought it while working in Hong Kong after it was presented as a way to build money for her later years.
The Numbers Raised Questions
Travis said she had been proud of the policy when she first met Orman but had not regularly checked its value. When Orman asked what the policy was worth, Travis said its cash value was $50,000. Against the $150,000 she said she had paid in premiums, that represented a $100,000 difference.
Orman criticised the arrangement and questioned the value Travis had received from the policy. However, the account does not establish how much the insurance agent earned or whether the agent acted improperly. The distinction is important because a difference between premiums paid and cash value does not, by itself, establish that money was lost through misconduct.
Cash Value Is Not the Same as Savings
Whole is not simply a savings account. The National Association of Insurance Commissioners (NAIC) says whole life provides coverage for the insured's lifetime while building cash value. That value comes from premiums after insurance costs and other charges are taken into account.
A policy's cash value therefore cannot be viewed in isolation. The policy also provides a death benefit, and policyholders may generally be able to borrow against or otherwise access the cash value, depending on the contract.
The $100,000 difference between Travis' reported premiums and cash value therefore should not automatically be described as a $100,000 loss.
Term Insurance Works Differently
Term life insurance generally provides coverage for a specified period and does not build cash value. The NAIC says term insurance typically costs less than permanent insurance and generally provides the largest amount of insurance protection for the premium dollar.
Whole life, universal life, and variable life are types of cash-value insurance. Their structures, costs, and potential values can differ, so the appropriate choice depends on the policyholder's circumstances and the reason for buying coverage.
Someone primarily seeking temporary protection for dependants may have different needs from someone seeking lifelong coverage.
Why Checking the Policy Matters
The NAIC advises consumers to understand whether a policy has cash value, how its values change over time, and which figures are guaranteed. It also recommends asking for an illustration showing future values and benefits.
Cash values can be relatively low during the early years of some policies and increase later. The precise pattern depends on the individual contract, making the policy documents essential when assessing its performance.
What Buyers Should Check
Anyone considering permanent life insurance should first establish why the coverage is needed and how long it is expected to last. Buyers should then examine the premium, death benefit, guaranteed cash values, and projected values. They should also understand the consequences of surrendering the policy, stopping premiums or borrowing against the cash value.
The NAIC advises people with existing policies not to cancel them before understanding the consequences and securing any replacement coverage they may need. For Travis, the experience highlights the importance of understanding what a financial product is designed to do. After 10 years of payments, the reported $150,000 in premiums and $50,000 in cash value prompted a closer examination of a policy she had viewed as part of her retirement planning.
© Copyright IBTimes 2026. All rights reserved.
- Recommended For You